The Next Best Action Playbook > Chapter 3: Next best action in practice: B2C examples by industry
Next best action in practice: B2C examples by industry
Every next best action program is the same five-step decision wearing a different costume. List the actions a customer is eligible for. Predict what the customer will do. Estimate how much each action would change that. Apply the constraints. Pick one, or pick none. The costume changes by industry, and so does the action that usually wins, which is why the examples below walk one customer each through a retailer, a streaming service, a mobile game, a digital bank and an insurer.
Every customer here is illustrative. The numbers are the kind a real program produces, and the decisions are the kind it makes, but none of these people exists. Read the examples for the shape of the decision, and notice how rarely the winning move is the discount.
Retail and ecommerce: the shopper who browsed twice and bought nothing
A home goods retailer with four million shoppers runs one decision more than any other: what to send someone who keeps looking and doesn’t buy.
Our illustrative shopper has browsed the standing desk category twice in ten days, bought a desk lamp eight months ago, and opened three of the last ten emails. The second category visit without a purchase is the trigger. Six actions are eligible: a restock and price alert, a 10% coupon, a free shipping offer, a feature in this week’s workspace editorial email, a retargeting ad, and nothing.
The propensity model says 0.42 for a desk purchase inside 14 days. The uplift estimates, learned from last year’s holdouts, are where the decision gets made:
| Action | Predicted uplift on purchase | Cost if she buys a $400 desk | Net incremental margin per contact |
|---|---|---|---|
| Editorial email featuring the desk | +7 points | ~$0 | ~$9.80 |
| Price alert | +2 points | ~$0 | ~$2.80 |
| Retargeting ad | +3 points | about $0.30 in impressions | ~$3.90 |
| Free shipping offer | +8 points | $25 | about -$1.30 |
| 10% coupon | +9 points | $40 | about -$7.80 |
| Nothing | 0 | $0 | $0 |
(Net margin assumes a 35% margin on the desk and that an offer’s cost is only paid when she buys. The coupon has the highest uplift and the lowest net, which is the whole story of promotional budgets in one row.)
Constraints finish it. She already received a promotional email on Tuesday, and the frequency cap is one a week, so the editorial email goes out Thursday with the desk in the first slot. The coupon stays in reserve, and for a good reason: if she hasn’t bought in seven days, the model re-scores her, and a coupon that’s net negative for a shopper at 0.42 can turn positive for the same shopper at 0.20, because there’s less “would have bought anyway” to pay for. A randomly selected twin of hers in the holdout gets nothing at all, so the retailer knows in thirty days whether any of this moved her.
Subscription and streaming: the subscriber whose hours collapsed
A streaming service with twelve million subscribers doesn’t decide by campaign calendar. It decides when a score moves.
Our illustrative subscriber is fourteen months in. He watched about twenty-two hours a month until two months ago; last month it was three. He visited the account page twice this week. His churn propensity crossed 0.55, up from 0.12 a month earlier, and the model’s top driver is engagement collapse, with price nowhere in the top five.
The eligible menu: a pause offer, a downgrade to the ad-supported tier, a personalized recommendation push about a new season in his top genre, a two-month discount, a service call, and nothing.
The driver decides most of the menu. Engagement-driven risk responds to content, so the recommendation carries the highest uplift at +11 points on 60-day retention. The discount’s uplift is +6 and it costs two months of revenue. The pause offer is +4. Then a constraint removes the discount anyway: the service allows one promotional discount per twelve months, and he used his nine months ago. The sleeping-dog check matters here too. Two account page visits mean he’s actively deciding, so silence is the wrong move for him, even though it’s the right move for the subscriber down the street who forgot he’s paying.
So the recommendation goes out as a push notification on Friday morning, timed to the season release, with an email the same evening for the people who ignore push. If there’s no watch session in ten days, the pause offer becomes the next best action. Our chapter on retention strategies by industry goes deeper on why content beats discounts for this kind of risk.
Gaming: the player stuck on level 34
In a mobile puzzle game with twenty million installs, the decision window is days, and the decision log for one player looks like this.
Day 5 after install. Eleven sessions so far, which is strong. Three consecutive sessions ended on level 34 without clearing it. No purchases. Propensity to lapse before day 7: 0.71. Propensity to make a first purchase this week: 0.18.
Eligible actions: a free booster, an easier variant of level 34, an invite to this weekend’s bonus-level event, a 50% off starter pack, a friend invite prompt, and nothing.
The uplift model, trained on last quarter’s randomized tests, ranks them. The difficulty tune lifts day 7 retention by about 15 points and costs nothing. The free booster lifts retention by 12 points but, for players with purchase propensity above 0.3, it cuts first-purchase propensity, because it hands out the thing they were about to buy. The starter pack lifts retention by 3 and purchase by 6. The event invite is worth 4 points, the friend prompt 2.
The decision: tune the level now. Hold the starter pack as the next best action for day 8, if he’s still playing. Never send the booster to a player who’s close to paying. This is the shape of the decision a social casino publisher put into production with us: the models predicted the likelihood of churn and of purchases in the coming week among the players who were active in the preceding 7 days, and the players who received the upsell offer showed ARPU increases of 11% in one game and 30% in another.
The lapse side has a do-nothing lesson too. SciPlay’s VP of marketing technologies put it plainly about lapsed players: “most will return within a few days or a week”, which is why the right action for a large share of them is to wait, and why the retargeting budget goes to the players who won’t.
Banking and fintech: the paycheck that moved
Next best action grew up in banks, and the classic decision is still the one worth studying: what to do when a customer’s primary status is slipping.
Our illustrative customer has had direct deposit with a digital bank for three years. The last two paychecks landed somewhere else. Card spend is down 60%. She has opened the app four times this week, mostly to check the balance. The model puts the probability of losing primary status within 60 days at 0.68, with “direct deposit redirected” as the leading driver.
| Step | What the program does |
|---|---|
| Eligible actions | Direct deposit switch-back bonus ($200), a six-month savings rate promotion, a fee waiver, a banker call, a credit line increase offer, nothing |
| Predicted uplift on keeping primary status | Bonus +14 points; banker call +9; rate promotion +5; credit line increase +2; fee waiver +1 |
| Cost per customer | Bonus $200 if claimed; call about $40; rate promotion about $60 on her balance; credit line increase carries risk cost; fee waiver about $12 |
| Constraints | Credit line offers require a fresh risk check (she passes); one outbound call per customer per quarter; bonus eligible once per 24 months (she’s eligible) |
| Arbitration | Expected value of the bonus is highest even at $200, because keeping a primary account is worth several hundred dollars a year in interchange and deposits |
| Chosen action | In-app switch-back bonus message now; banker call becomes the next best action if the deposit hasn’t returned in 14 days |
| Measurement | She’s in the treated group; a random 10% of customers with the same trigger get the old rules, which would have sent a generic savings promotion |
Two things in that table carry over to every industry. The action that wins is the one aimed at the driver, and the second-best action is scheduled, not discarded. A decisioning program is a sequence of next best actions, each one conditioned on what the last one did.
Insurance: seventy days before renewal
An auto insurer’s decision has a clock on it. Renewal is in seventy days, a 12% rate increase is coming, and our illustrative policyholder has logged in twice this week and downloaded her declarations page. Shopping propensity: 0.6. Switching propensity: 0.35.
Eligible: a proactive renewal review call, a bundling offer on her home policy, a telematics discount enrollment, a loyalty credit, and nothing. Uplift on renewal: the review call +10, the bundle +7, telematics +4, the loyalty credit +3. The call wins, with telematics enrollment as the thing the agent offers during it, timed for 45 days before renewal, when the shopping window usually opens.
The sleeping-dog check does the most work in insurance. A policyholder with low shopping propensity and no sign of deliberation is often better left alone until the renewal notice; outreach “about your renewal” can start the shopping it was meant to prevent. For her, with two logins and a downloaded declarations page, the deliberation has already started, so the call is the right move. For her neighbor, who hasn’t logged in since March, nothing is.
What the five examples have in common
Strip the costumes off and the same machine is running in all five.
| Retail | Streaming | Gaming | Banking | Insurance | |
|---|---|---|---|---|---|
| Trigger | Second category visit, no purchase | Churn propensity crossed 0.55 | Three sessions stuck, lapse propensity 0.71 | Primary-status risk 0.68 | Renewal in 70 days, shopping propensity 0.6 |
| Winning action | Editorial email | Content recommendation | Difficulty tune | Switch-back bonus | Review call |
| Why the discount lost | Highest uplift, negative net | Ineligible, and the driver was content | Would cannibalize a likely purchase | Beaten on expected value | Starts the shopping it meant to stop |
| Next best action queued | Coupon in 7 days | Pause offer in 10 days | Starter pack on day 8 | Banker call in 14 days | Bundle at renewal |
Three patterns hold. The winning action is aimed at the driver behind the prediction, which is why the propensity model has to deliver reasons and a window, never a bare score. The discount is rarely first, and the uplift model is what demotes it, by showing that its net value trails cheaper actions even when its raw lift leads. And “nothing” is on every menu, measured like any other action, which is the subject of the chapter on measuring decisioning impact.
If your lifecycle team is still deciding by segment and calendar, the expansion stage of the lifecycle playbook shows the same decision from the journey builder’s side.
Where we come in
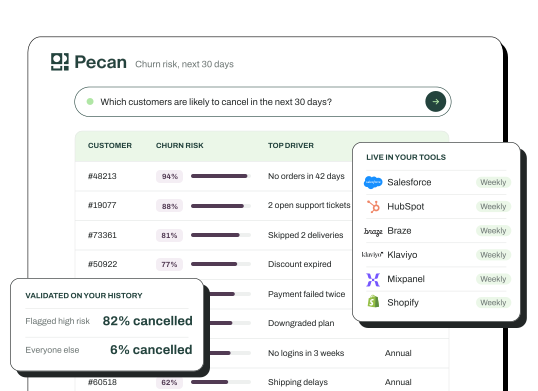
The predictions in every example above (the propensities, the drivers, the uplift per action) are the part that used to need a data science team. You bring your historical customer data and the decision you want to make, the Predictive AI Agent reads that data as it is, trains and validates the propensity and uplift models, and we own the outcome, with scores and drivers live in the CRM, ESP or decisioning tool your team already uses. The arbitration rules stay yours, in plain language, and the next decision runs on the same foundation.
Predict the right move for every customer:
Book a demo